
Organized financial records help small businesses demonstrate their financial position when applying for government grants, business loans, and other assistance programs. Funding organizations often examine income statements, cash flow reports, existing debts, and supporting documents before making decisions. The U.S. Small Business Administration (SBA) identifies financial statements and projections as important parts of business funding requests. These records help lenders understand business performance and assess repayment capacity.
Preparing these documents can become challenging when businesses have limited accounting resources. Some owners manage everything internally, while others use business process outsourcing (BPO) services for financial administration. Businesses may choose to outsource bookkeeping when transaction volumes increase or regular reporting becomes difficult. Regardless of the approach, financial information must remain accurate, complete, and supported by reliable documentation.
Why Accurate Financial Records Matter for Funding Applications
Financial records provide evidence of how a business earns, spends, and manages money. Lenders examine these details to understand whether the company generates enough cash to meet existing obligations and additional repayments. Grant administrators may review financial information to assess eligibility, financial stability, and compliance with program requirements.
The U.S. Small Business Administration recommends that established businesses include historical income statements, balance sheets, and cash flow statements when preparing comprehensive funding proposals. Meanwhile, Grants.gov advises applicants to review each funding opportunity carefully because eligibility rules differ between programs.
However, documentation problems can complicate applications. Missing receipts, incorrectly recorded transactions, incomplete statements, and differences between bank records and accounting reports can raise questions. Financial information also matters in other assistance programs.
For example, financial aid eligibility estimates for students have historically considered household income, available resources, and education costs. Although business funding follows different assessment rules, both processes show why applicants should maintain accurate records and understand financial requirements before applying.
A Step-by-Step Guide to Preparing Financial Records for Business Funding
Preparing financial documents becomes easier when business owners follow a clear process. The following seven steps help organize financial information, identify reporting problems, and improve the reliability of funding applications.
1. Review Financial Documentation Requirements
Start by examining the application instructions provided by the lender or financial assistance program. Requirements differ depending on the funding amount, business structure, and purpose of the assistance.
Commonly requested documents may include financial statements, tax returns, bank records, debt information, and business plans. Some programs also require financial projections or specific reporting periods. Create a checklist based on the actual application requirements. Confirm submission deadlines, acceptable document formats, and whether professional certification is necessary.
2. Organize Income and Expense Records
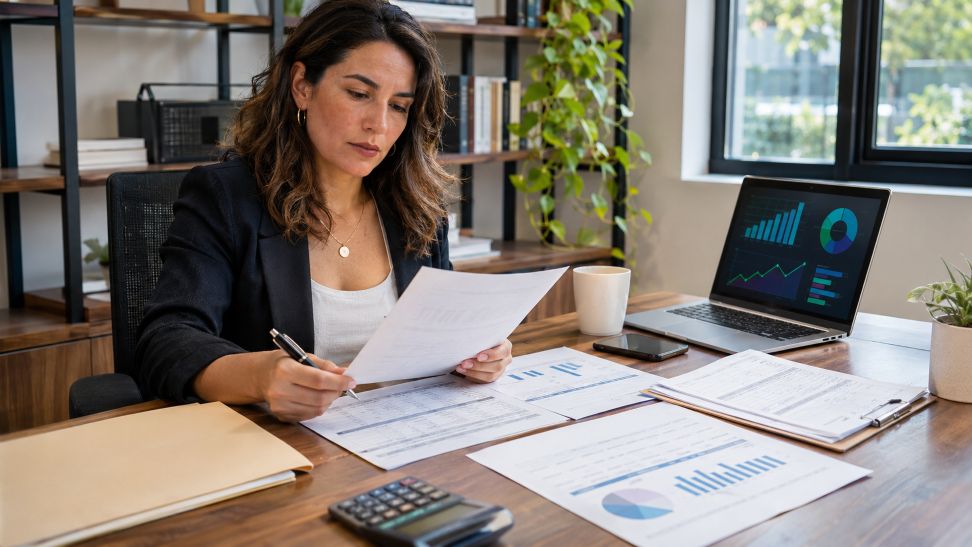
Collect financial documents that explain business transactions. These include customer invoices, supplier receipts, payment confirmations, payroll records, and bank statements.
The Internal Revenue Service (IRS) explains that supporting documents establish the details behind recorded income and expenses. Businesses should organize these records by date, transaction category, or accounting period.
Digital folders can simplify document retrieval. However, electronic records still need proper organization, accurate information, and secure storage. Keep personal and business transactions separate whenever possible.
3. Reconcile Business Accounts
Compare bookkeeping entries against bank statements and other payment records. This process helps identify transactions that were omitted, duplicated, or entered incorrectly.
For example, a business might record a supplier payment twice or overlook a customer deposit. Either mistake could distort the reported cash balance.
The IRS recommends reconciling business checking accounts to identify errors. Investigate differences, document corrections, and retain supporting evidence. Regular reconciliation also reduces the amount of corrective work required before future applications.
4. Prepare Financial Statements
Once transaction records are organized, prepare the financial reports requested by the funding organization. Three common statements serve different purposes:
- Income statement: Summarizes revenue, expenses, and profit or loss over a specified period.
- Balance sheet: Presents business assets, liabilities, and equity at a particular date.
- Cash flow statement: Shows how money enters and leaves the business through its activities.
These statements should use consistent accounting periods and reliable figures. Business owners should also explain unusual expenses, seasonal changes, or significant revenue fluctuations when relevant. Financial projections must be clearly distinguished from historical results.
5. Review Outstanding Debts and Obligations
Existing financial commitments can affect a business’s ability to handle additional borrowing. Prepare an updated list of outstanding loans, credit balances, supplier obligations, and scheduled repayments.
Include payment amounts, interest rates, remaining balances, and maturity dates when applicable. Review whether these obligations match the liabilities reported in financial statements.
Accurate debt information helps lenders evaluate repayment demands alongside business cash flow. It also allows owners to assess whether taking on another financial obligation is practical.
6. Consider Professional Bookkeeping Assistance
Some businesses have sufficient internal resources to maintain their records independently. Others may need external assistance when financial transactions become more complex or reporting deadlines increase.
Professional bookkeeping providers can help organize transactions, reconcile accounts, and produce recurring reports. However, service arrangements differ. Owners should review costs, confidentiality practices, reporting responsibilities, and access to financial information before selecting a provider.
External assistance can improve documentation processes, but it does not automatically establish eligibility or guarantee funding approval. Business owners remain responsible for providing truthful information and meeting applicable program requirements.
7. Check Records Before Submission
Perform a final review before sending the application. Verify that financial statements reflect the correct periods and agree with supporting records.
Confirm that requested attachments are included, document names are clear, and figures remain consistent throughout the application. Explain any material discrepancies rather than concealing them.
It is also useful to retain copies of submitted documents and related correspondence. These records make it easier to answer questions or provide additional information during the review process.
Maintaining Financial Readiness Beyond One Application
Preparing records should be an ongoing business practice rather than a task completed only when funding becomes necessary. Consistent bookkeeping helps owners monitor operating expenses, identify financial pressures, and make informed decisions.
The IRS identifies accurate recordkeeping as important for preparing financial statements, tracking income, and supporting tax reporting. These benefits remain valuable whether a company receives financial assistance or continues operating without additional funding.
Conclusion
Successful financial preparation begins with reliable records and transparent reporting. Small businesses should understand funding requirements, organize supporting documents, reconcile accounts, and review outstanding obligations before applying.
Whether records are maintained internally or with professional support, accuracy remains essential. Strong financial management helps businesses communicate their financial position clearly and prepare for future funding opportunities without assuming approval is guaranteed.